White paper · Optimise · 22 min read
Sources: Hyster-Yale Asia Pacific, Super Retail Group and Bunzl case studies published on pricinginsight.com; the Bunzl override figure is from the Pricing Periodic Table, CXO Edition, which reports it with the published EBIT result. All three are realised results as reported by Pricing Insight, not independently audited, and none is a benchmark for another business.
Discounting can drive immediate sales and achieve various strategic goals, but it also carries risks that can undermine long-term profitability and brand equity. This article analyses eleven strategic reasons for discounting, detailing when and why each might be used, the potential benefits, and the risks involved.
The question this paper answers
How do I stop sales reps over-discounting, and reduce the discount overrides that follow, without losing the flexibility a discount gives?
Key takeaways
- Discounting can support deal closure, market penetration, cash flow, customer loyalty and other business objectives, but can also undermine long-term profitability.
- Frequent discounts can condition customers to delay purchases or expect lower prices, making it harder to maintain regular pricing.
- Businesses can use approval mechanisms and discount thresholds to limit excessive discounting while retaining flexibility for market conditions.
- Monitoring margin impact, offer take-up and return, customer segments and long-term customer value helps assess discounting strategies.
Five Pricing Insight clients show what those controls are worth in practice. Hyster-Yale Asia Pacific, Super Retail Group, Bunzl, Tradelink and Farmlands each appear below in the same six-part form: the problem and what it put at risk, why it was hard to fix, what Pricing Insight did, the outcome with its status, the benefit to the client, and the Pricing Periodic Table elements the work built.
01Businesses discount for eleven reasons, and each reason carries its own risk to future price
Discounting can serve various strategic purposes but needs to be applied thoughtfully to avoid unintended consequences. Below, we examine 11 key reasons for implementing discounting and the associated benefits and risks.
1. Accelerating deal closure
Discounts can be critical in speeding up deal closure, particularly in B2B settings where decision timelines are extended, and competitors are aggressive. A well-timed discount can push a hesitant buyer over the edge, especially when combined with a sense of urgency, such as an impending deadline or limited-time offer.
Strategic benefits: Accelerating the sales cycle can free up resources and enable sales teams to focus on acquiring additional customers. It also reduces the risk of losing the deal to a competitor.
Risks: Frequent use of discounts to close deals can lead to customers delaying purchases in anticipation of future discounts, ultimately slowing down the overall sales process.
2. Enhancing volume and market penetration
Volume-based discounts are particularly effective during product launches or when entering new markets. By reducing the price barrier, companies can quickly attract price-sensitive customers, establish a presence, and gain market share.
Strategic benefits: Early market penetration can provide a competitive advantage, especially in industries with significant first-mover benefits. Increased volume can also lead to economies of scale, reducing per-unit costs.
Risks: The downside is that customers may come to expect these lower prices as the norm, making it difficult to raise prices later. Additionally, the increased volume must be sustained to maintain profitability, which can be challenging if demand is driven solely by price.
3. Driving cash flow
Discounts can be used tactically to generate immediate cash flow during times of financial pressure, such as an economic downturn or a period of low sales. This approach is often employed as a short-term measure to maintain liquidity.
Strategic benefits: Generating cash flow quickly can be crucial for meeting immediate financial obligations, such as payroll or supplier payments. It can also provide the capital needed for reinvestment in other business areas.
Risks: Relying on discounts to drive cash flow can create a cycle of dependency, where customers expect continuous discounts, and the business struggles to return to regular pricing. This can erode long-term profitability.
4. Generating economies of scale
Discounts that incentivise bulk purchases can help businesses achieve economies of scale. This is particularly relevant in industries with high fixed costs, where increasing production can significantly reduce per-unit costs.
Strategic benefits: Achieving economies of scale can lead to a more competitive cost structure, enabling the company to offer lower prices or enjoy higher margins. It also strengthens the company’s market position by increasing barriers to entry for competitors.
Risks: The primary risk is overproduction, which can lead to excess inventory and increased holding costs if demand does not match the increased production levels.
5. Rewarding repeat business and contract renewals
Discounts tied to a renewal, a multi-year agreement or a committed annual spend reward customers for the business they bring, not for asking. The discount is earned against a condition the customer meets: a volume threshold, a term, a share of category spend or an ordering pattern that lowers cost to serve.
Strategic benefits: Committed customers give a stable revenue base and lower acquisition costs, and a discount written against a measurable commitment can be checked each year and withdrawn if the commitment is not met.
Risks: Over-reliance on discounts to keep customers can erode margins and reduce the perceived value of the product or service. Service levels, account support and terms the customer values often hold a renewal at lower cost than a deeper discount.
6. Avoiding inventory obsolescence
Discounts can effectively move excess or slow-moving inventory, particularly for products with a limited shelf life or that are subject to technological obsolescence. This is commonly used in retail and manufacturing industries.
Strategic benefits: Clearing out old inventory frees up warehouse space and capital, allowing the business to invest in new, more profitable products. It also reduces the risk of having to write off obsolete stock.
Risks: If customers come to expect regular inventory clearance sales, they may delay purchases until prices drop, disrupting regular sales cycles and inventory management.
7. Service recovery and goodwill credits
A one-off credit after a late delivery, a quality fault or a billing error repairs a relationship at a known cost. Unlike the earned discounts in section 5, it rewards nothing the customer does; it settles a specific event.
Strategic benefits: A fast, proportionate credit keeps the account and protects the price list, because the concession is attached to the event rather than to the product price.
Risks: If not handled carefully, goodwill credits set a precedent and customers come to expect them when the circumstances do not warrant it. Each credit carries a reason code, a value limit and an end date, and is issued as a credit note rather than a change to the customer’s price.
8. Dealing with inventory and shelf space constraints
In scenarios with limited physical or virtual shelf space, discounting can help quickly move products to make room for higher-margin items or new product lines.
Strategic benefits: Optimising shelf space ensures that the most profitable products are given priority, which can enhance overall sales performance and inventory turnover rates.
Risks: The main risk is that discounting to clear space can devalue products, leading customers to question the original pricing. Additionally, it can create a perception of lower quality or excess supply, which may deter future purchases.
9. Capturing seasonal buying opportunities
Seasonal discounts are timed to coincide with periods of increased consumer spending, such as holidays or back-to-school seasons. This strategy is widely used in retail but applies to other sectors with cyclical demand.
Strategic benefits: Seasonal discounts can drive significant sales volumes quickly, taking advantage of heightened consumer interest. They also help businesses clear inventory that may not be as relevant after the season ends.
Risks: Over-reliance on seasonal discounting can lead to customers only purchasing during these periods, reducing sales during off-peak times. This can also increase competition, as many companies adopt similar discounting strategies during these periods.
10. Creating an opportunity to cross-sell or up-sell
Discounts can be strategically used to encourage customers to purchase additional products or higher-value items. Offering a discount on a complementary product can enhance the overall sale.
Strategic benefits: Cross-selling and up-selling through discounting can increase the average transaction value and improve overall profitability. It also deepens customer engagement with the brand by introducing them to a broader range of products.
Risks: If not executed well, customers may only purchase the discounted items and ignore the full-priced products, leading to a decrease in overall profitability. Additionally, frequent discounting of related products can lead to the same conditioning issues seen with direct product discounts.
11. Responding to competitive pressures
In highly competitive markets, discounting can be necessary to match or undercut competitors’ pricing. This approach is often used defensively to protect market share and prevent customer attrition.
Strategic benefits: Price matching or undercutting can help maintain customer loyalty and market position, particularly in industries where price sensitivity is high. It can also prevent competitors from gaining a foothold.
Risks: Engaging in price wars can lead to significant margin erosion and may harm the long-term financial health of the business. Assessing whether the market share gained through discounting justifies the potential loss in profitability is essential.
02Every discount has a break-even volume, and anyone allowed to discount should know it
One rule sits under all eleven reasons. Break-even volume is the extra volume a discount must bring in for gross profit after the discount to equal gross profit before it, and it equals the discount divided by the gross margin less the discount. The thinner the margin, the more volume each point of discount has to buy, and at a 20 per cent margin a 20 per cent discount can never earn its cost back.
| Gross margin | 5% discount | 10% discount | 20% discount |
|---|---|---|---|
| 40 per cent | +14% volume | +33% volume | +100% volume |
| 30 per cent | +20% volume | +50% volume | +200% volume |
| 20 per cent | +33% volume | +100% volume | Never breaks even |
Exhibit 1. Extra volume needed to earn the same gross profit after a discount. Extra volume = discount ÷ (gross margin less discount); at a 30 per cent margin and a 5 per cent discount, 5 ÷ (30 less 5) = 20 per cent. Illustrative arithmetic from the Pricing Periodic Table, CXO Edition.
Few sellers can do the sum unaided. A seller who cannot work out what a discount costs gives it without knowing the size of the decision, and the approval controls in section 03 then carry the whole load.
Super Retail Group
Four retail brands · Ad hoc discounting cut by up to half · Realised
| Client and problem | Pricing strategy was not aligned across Super Retail Group’s four retail brands, and ad hoc discounting and markdowns were not held to common governance, so each brand gave away margin on its own terms. |
| Challenge | The people making discount decisions did not have the arithmetic behind them. The diagnostic tested the pricing maths behind every discount: at a 30 per cent gross profit, a 20 per cent discount needs 200 per cent more volume to earn the same gross profit dollars. |
| What Pricing Insight did | A pricing diagnostic across the four brands, followed by pricing strategy aligned across the brands, markdown governance and discount control. |
| Outcome | Ad hoc discounting reduced by up to 50 per cent across the four brands, a realised result as published. |
| Benefit to the client | Less margin given away through unplanned discounts, and one set of rules for markdowns in place of four, which lowers the group’s exposure to discount-driven margin erosion in any single brand. |
| Periodic Table elements built | 32 Nu Commercial numeracy; 61 Da Discount authority and controls; 06 Ws Written pricing strategy; 51 Dt Discount structure and tiers. |
03Six controls keep discounting tied to profit, and each has a cost if set badly
Implementing sound controls and monitoring key metrics is critical to effectively managing discounting strategies. Here are six advanced techniques to consider:
1. Discount approval mechanisms
Implementing a tiered approval process ensures that discounts align with strategic objectives and are only offered when necessary. Data analytics should support this process to predict the impact on margins and long-term customer value.
Benefit: Ensures discounts are strategic rather than reactionary, protecting margins and supporting long-term objectives.
Negative considerations: A complex approval process can slow decision-making, potentially causing delays in time-sensitive negotiations.
2. Predefined discount thresholds
Set clear discounting thresholds based on product categories, customer segments, and sales volumes. These thresholds should be dynamic, adjusting to market conditions and internal performance metrics.
Benefit: Provides a safeguard against excessive discounting, helping to maintain profitability.
Negative considerations: Rigid thresholds can reduce flexibility, making it difficult to respond quickly to unique market opportunities or competitive pressures.
3. Monitoring margin impact
Track the impact of discounts on gross margins regularly. This KPI is crucial for maintaining profitability and ensuring that discounting strategies do not inadvertently lead to financial losses.
Benefit: Monthly reporting shows the effectiveness of discounting strategies and allows timely adjustments.
Negative considerations: Focusing too heavily on margin impact can overlook other important factors, such as customer lifetime value or market share growth.
4. Customer segmentation analysis
Advanced segmentation allows targeted discounting that maximises immediate sales and long-term customer value. Your segmentation strategy should consider factors such as purchase history, price sensitivity, and cross-sell potential.
Benefit: Optimises discounting strategies by focusing on the most profitable customer segments.
Negative considerations: Complex segmentation models require significant data analysis capabilities, which may not be feasible for all businesses.
5. Tracking take-up and the return on each offer
Purpose: For every structured offer (a volume break, an early-payment term, a project price or a promotional deal), measure how many eligible customers or orders used it and what it returned: the extra volume and gross profit dollars it brought in, against the margin it gave up. An offer most customers use but that brings no extra volume is a price cut; one few customers use may be set at the wrong threshold.
Benefit: Shows which offers earn their cost and which should be reset or withdrawn, based on how customers actually buy.
Negative considerations: High take-up does not on its own mean profit, particularly if the discount is deep; the measure is read with the break-even volume in section 02.
6. Long-term customer value assessment
Purpose: Evaluate the long-term value of customers acquired through discounts. If these customers have lower retention rates or only purchase when discounts are offered, your discounting approach may need to be refined.
Benefit: Ensures that discounting strategies contribute to sustainable growth rather than short-term gains.
Negative considerations: This analysis requires reliable data tracking and can be resource intensive.
Two clients show the first two controls at work. At Hyster-Yale Asia Pacific the approval mechanism was a single dealing desk; at Bunzl the thresholds took the form of price ladders and discount guardrails by SKU and segment. In both, the control was set from the economics of the product and the customer, not from a flat percentage.
Hyster-Yale Asia Pacific
Forklift wholesaler · A$100k EBIT loss to A$3m gain · Realised
| Client and problem | The forklift wholesaler was selling machines below cost and losing about A$100,000 at the EBIT line, with discounts given at will. |
| Challenge | Sellers were paid on volume, so the person giving the discount barely felt its cost, and discounts were available across the range rather than only on the models where the business had pricing power. |
| What Pricing Insight did | Project Blackbird price optimisation. One dealing desk handled every sale, discounts were limited to the 5 to 7 tonne machines where the business had pricing power, accessories and parts were repriced, and sales effort was aligned to the right segments. |
| Outcome | From a A$100k EBIT loss to a A$3m EBIT gain within 12 months, a realised result as published. |
| Benefit to the client | A loss-making business returned to profit at the operating line in one year without a new product or a cost program, and ad hoc discounting was eliminated. |
| Periodic Table elements built | 40 Dd Deal desk and negotiation governance; 61 Da Discount authority and controls; 10 Pp Pricing power; 08 Sg Segment and channel strategy. |
Bunzl
Global distributor · A$5.7m EBIT improvement · Realised
| Client and problem | Bunzl’s margins were shrinking as volume grew, and frequent overrides in tenders took prices below where the business needed them. |
| Challenge | The range ran to 18,000 SKUs across more than one division, and tender prices were set deal by deal through overrides rather than from a price structure. |
| What Pricing Insight did | Project Blackbird price optimisation: price ladders by SKU and customer segment, discount guardrails that set how far a price could move, and a two-division pilot before wider rollout. |
| Outcome | A$5.7m EBIT improvement reported following price optimisation across 18,000 SKUs, realised. The CXO Edition reports, for the same work, 8 points of gross margin on targeted SKUs, overrides down 35 per cent and 98.3 per cent of customers kept, all realised. |
| Benefit to the client | Higher margin with almost all customers retained, so tighter discount control did not cost the customer base, and a third fewer overrides left less margin exposed in tenders. |
| Periodic Table elements built | 54 Co Price corridors and exceptions; 52 Rl Price relativities and volume breaks; 46 Pm Price modelling; 18 Tp Tender and project pricing. |
04The override report shows a distributor where the controls are failing, and the cause decides the fix
Product, person, customer. An override is any sale below the system or agreed price. Margin monitoring shows where margin goes in total; override analysis shows how it goes, quote by quote, and where overrides cluster says what is probably wrong. A reason code on every override separates the ones that win profitable work from the ones that repeat an old concession.
| Overrides cluster on | What is probably wrong | Who fixes it |
|---|---|---|
| A product line | The price band or base price for that line | Pricing manager |
| A person | The authority level, or the coaching | Sales director |
| A customer | The agreement, which needs renegotiating | Account owner |
Exhibit 2. Where overrides cluster tells you what to fix. Report overrides by product, by person and by customer each month. Source: Pricing Periodic Table, CXO Edition, Figure 9.4.
Report alone does not change behaviour. A morning override report that goes to managers with no owner and no follow-up becomes a record of margin already lost, and every route around approval, whether a price loaded on request, changed after approval or overridden at the counter, shows deals inside policy while real prices sit below it. Two distribution clients show both sides of the problem.
Tradelink
Wholesale and distribution · 200+ branches · A$10.8m opportunity identified
| Client and problem | Across more than 200 branches, staff did not trust the price book or its price levels, so branches and reps overrode and contract-priced around them. Inconsistent price setting and unexplained overrides were among the issues staff raised most often in the pricing diagnostic. |
| Challenge | Override reports already reached managers each morning, and one staff member’s response was “then what?”. Supplier rebates and price support sat behind invoice cost, so many staff were guessing margins, some special quotes went out at nil invoice margin on the assumption rebates would cover them, and delegated authority levels were, in one staff member’s words, “not understood company wide”. |
| What Pricing Insight did | A pricing diagnostic across the branch network, then work to replace overrides with structure and sales enablement. |
| Outcome | An A$10.8m annualised margin opportunity identified, as published. Identified, not realised. |
| Benefit to the client | A margin opportunity sized against named causes, in place of overrides that were reported daily but not acted on, which reduces the network’s exposure to sales priced on rebates that may not cover them. |
| Periodic Table elements built | 44 Or Override and discount analysis; 49 Lp List price alignment; 55 Tn True net price program; 61 Da Discount authority and controls. |
Farmlands
New Zealand rural co-operative · A$3.5m to A$6.2m EBIT opportunity identified
| Client and problem | Farmlands’ chief executive estimated that about 80 per cent of lost margin sat in sales under A$2,500, and the leadership team was considering removing cost price from sellers’ view to stop it. |
| Challenge | The cause was not yet known. If sellers were editing prices below the recommended sell, controls at the point of sale would fix it; if the standard prices were too thin, hiding cost would change nothing, and a comparable distributor that had removed cost visibility saw slower sales and sellers who stopped owning margin. |
| What Pricing Insight did | Recommended a test first: compare the share of sub-A$2,500 transactions with a manual price edit against those sold at the standard price. Then three levers together: cost shown to sellers with a protective mark-up, delegated authority bands by role with automatic escalation to a manager, and margin-linked pay. All recommended; no result is reported for them. |
| Outcome | An A$3.5m to A$6.2m EBIT opportunity identified through aligning teams, controlling overrides and simplifying national pricing structures, as published. Identified, not realised. |
| Benefit to the client | Avoided a control that would have added friction without fixing a base pricing problem, and put override control, authority and pay on one plan, which lowers the risk of a margin fix that sellers work around. |
| Periodic Table elements built | 44 Or Override and discount analysis; 61 Da Discount authority and controls; 33 In Sales incentives; 57 Dq Pricing master data. |
05Discounting stays in balance with profit when the controls are measured and owned
When applied strategically, discounting can be a powerful tool for achieving various business objectives. However, it must be managed precisely to avoid eroding profit margins, devaluing the brand, or conditioning customers to expect lower prices. By understanding the specific reasons for discounting and implementing advanced controls and KPIs, businesses can use discounts to support both short-term performance and long-term growth. The key is maintaining a balance, ensuring that discounting enhances rather than undermines your pricing strategy.
Pricing Insight builds discount structures, approval levels and override reporting from a business’s own transaction data, across 160+ engagements in manufacturing, wholesale and distribution. To discuss your discounting controls, contact us on +61 410 534 099, at info@pricinginsight.com.au or through our contact page.
Three things are safe to read from the five cases. Speed: at Hyster-Yale Asia Pacific the result came within 12 months, and the control that produced it, one dealing desk, was a change in who approves a price rather than a new system. Size: the realised results run from up to half of ad hoc discounting removed at Super Retail Group to A$5.7m of EBIT at Bunzl and a swing from a A$100k loss to a A$3m gain at Hyster-Yale, and the identified opportunities are A$10.8m at Tradelink and A$3.5m to A$6.2m at Farmlands. Risk: in each case the work closed a route by which margin left the business without a decision, whether discounts at will, overrides in tenders, quotes at nil invoice margin or price edits on small sales. Identified opportunities are not results, and none of these figures is a benchmark for another business.
06The Pricing Periodic Table elements this paper builds
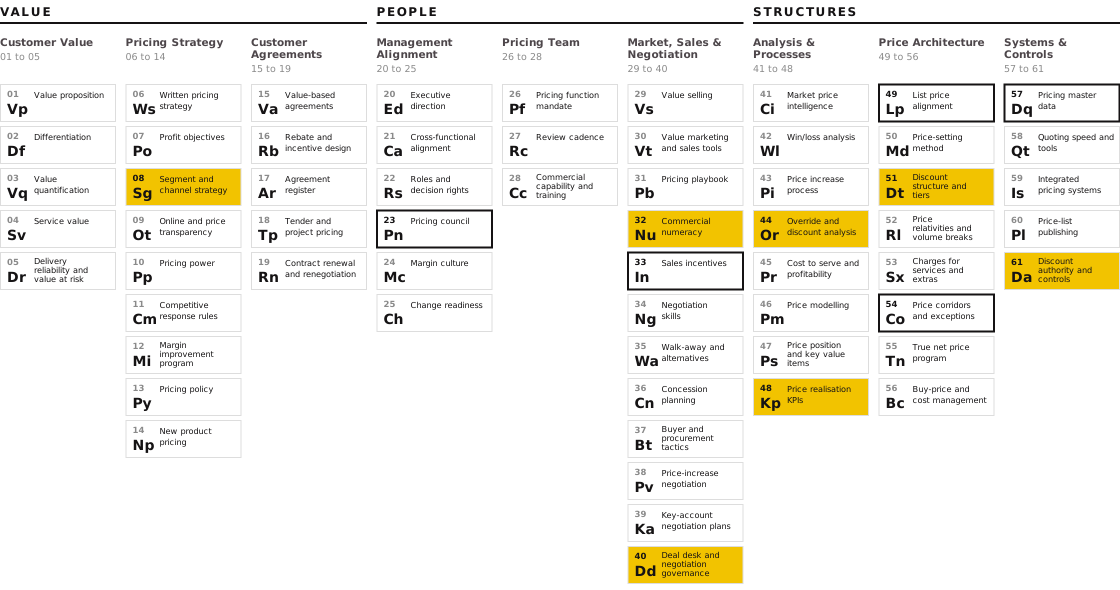
The Pricing Periodic Table sets out 61 elements of pricing capability in nine domains, across Value, People and Structures. Seven are built by the controls in this paper: 61 Da Discount authority and controls (approval mechanisms), 51 Dt Discount structure and tiers (predefined thresholds), 48 Kp Price realisation KPIs (margin impact and long-term customer value), 08 Sg Segment and channel strategy (customer segmentation), 44 Or Override and discount analysis (the override report), 32 Nu Commercial numeracy (break-even volume) and 40 Dd Deal desk and negotiation governance (deals above a seller’s authority). Five are depended on: 33 In Sales incentives decides what a seller feels when a discount is given, 54 Co Price corridors and exceptions and 49 Lp List price alignment set the prices the thresholds are measured from, 57 Dq Pricing master data supplies the cost the controls read, and 23 Pn Pricing council owns the limits.
The client cases map onto these elements directly. Hyster-Yale Asia Pacific built 40 Dd and 61 Da through a single dealing desk, Super Retail Group built 61 Da and 51 Dt across four brands where the diagnostic tested 32 Nu, Bunzl built thresholds through 54 Co price guardrails, and Tradelink and Farmlands began with 44 Or, where the override evidence decides whether the fault sits with the seller, the price book or the cost data in 57 Dq.
07Frequently asked questions
How do I stop sales reps over-discounting in a B2B business?
Give sellers the break-even arithmetic, set approval bands by margin with a named approver for each, enforce them in the system at quote and order entry, and report discounts and overrides monthly by rep, product and customer. Pay that rewards margin as well as revenue makes the seller feel part of the cost. Hyster-Yale Asia Pacific moved from a A$100k EBIT loss to a A$3m EBIT gain within 12 months after one dealing desk replaced discounts given at will, a realised result.
How do I reduce discount overrides in a distribution business?
Report every override by product, person and customer with a reason code, and let the cluster decide the fix: a product cluster points to the price band, a person cluster to authority or coaching, a customer cluster to the agreement. Close the routes around approval, and test whether sellers are overriding or the standard price is too thin before restricting what they see. Bunzl cut overrides by 35 per cent with price ladders and discount guardrails, a realised result reported with a A$5.7m EBIT improvement.
Should sales reps see cost and margin?
Yes, within authority limits. A seller who cannot see margin cannot know what a discount costs, and hiding cost does not fix a standard price that is too thin. At Farmlands the recommendation was cost shown with a protective mark-up, authority bands by role with automatic escalation and margin-linked pay, applied together; no result is yet reported for these recommendations.
Which discount KPIs should be reported by rep?
Margin impact of discounts, price realisation and override share by rep each month, beside approval requests by band and how many were approved unchanged. Each measure is defined once, measured like for like and reconciled to reported revenue and gross margin. Redemption rates and the long-term value of customers won on discount show whether a discount bought lasting business or only a sale.
How tight should discount approval limits be?
Tight enough to stop the deals that give margin away, and no tighter. A complex approval process slows decisions and pushes staff to find routes around it; at Tradelink, staff described approval for a price match taking days and lost sales while they waited. Set limits by product class and deal size, lift any limit where nearly every request passes unchanged, and test the lowest floor against the cost of doing business.
08How Pricing Insight helps
The paper’s emphasis on approval thresholds and margin measures can be put into practice through Pricing Capability & Governance. It helps set pricing roles, decision rights, discount approvals, price floors and a Pricing Council, giving teams a clear framework to limit excessive discounting while retaining flexibility.
The work runs in three stages, each drawing on evidence from the client’s own transactions. Pricing Insight has completed 160+ engagements, and price optimisation programs return between 5 and 10 times their cost in year 1.
Diagnose
Twelve months of invoices by seller, customer and product through the Strategic EBIT Opportunity & Risk Diagnostic. Discounts and overrides by rep, product and customer, approval requests by band, the pricing maths of everyone with discount authority, and every route around approval, sized against a baseline finance accepts.
Optimise
Approval bands by margin with named owners, thresholds by product category and customer segment, and floors tested against the cost of doing business. The EBITDA Improvement Program sets the target prices and price ladders the bands are measured from, with ERP-ready files.
Transform
Sellers trained in break-even maths, value selling and concession planning through Negotiation Training & Value-Based Selling. Pay tied to margin, and the override report and discount KPIs in the monthly pack, reviewed by a Pricing Council.
What did your sales team give away in discounts last month, and what did it buy?
A first conversation establishes how this applies in your business and whether a diagnostic is warranted. Ron Wood, +61 410 534 099.
Ron Wood is the Founder and Managing Director of Pricing Insight, an Australian pricing strategy consultancy he established in 2007. He has worked in pricing for 30 years, first as a pricing and commercial manager in consumer goods, building materials and capital equipment, and since then across 160+ engagements in Australia, New Zealand, South East Asia, India, the United States and the United Kingdom. He also founded Pricing University and is the author of the Pricing Periodic Table, CXO Edition.
To discuss how this applies to your sales team, contact Ron Wood at info@pricinginsight.com.au or on +61 410 534 099, or visit Pricing Insight.
Hyster-Yale Asia Pacific, Super Retail Group and Bunzl figures are realised results as published in Pricing Insight case studies; the Bunzl gross margin, override and customer retention figures are as reported in the Pricing Periodic Table, CXO Edition. Tradelink and Farmlands figures are identified opportunities, not results. The Super Retail Group diagnostic findings, the Tradelink staff comments and the Farmlands recommendations come from Pricing Insight diagnostic and advisory work; staff are quoted by role only. The break-even table is illustrative arithmetic. Results are as reported by Pricing Insight and have not been independently audited. No figure in this paper is typical or guaranteed.